Does Home Insurance Cover Roof Replacement in Ontario?
One of the most common questions homeowners ask after roof damage is whether their home insurance will pay for a replacement. It is an important question, and the answer is: it depends. Home insurance in Ontario generally covers roof damage that is sudden and accidental, such as storm damage, but it generally does not cover a roof that has simply worn out with age. Understanding the difference, and how factors like roof age and depreciation come into play, helps you know what to expect before you file a claim.
This article offers general guidance on how roof insurance coverage typically works in Ontario. Every policy is different, so the only definitive source for your situation is your own policy and your insurance provider. McKay Roofing is not an insurance advisor, but after more than 50 years helping Ottawa Valley homeowners, we understand the process well and can help in specific ways described below.
What Home Insurance Typically Covers
Most Ontario home insurance policies cover roof damage that results from sudden, accidental, and unforeseen events. These are commonly referred to as covered perils, and they typically include:
- Wind and storm damage, such as shingles blown off in a windstorm
- Hail damage
- Damage from fallen trees or branches
- Fire damage
- Weight of ice and snow in some cases
When a roof is damaged by one of these sudden events, insurance will often cover the repair or, if the damage is extensive enough, the replacement. Our guide on inspecting your roof for storm damage covers what to look for after a major weather event, and the hail damage page covers that specific peril.
What Is Usually Not Covered
The most important thing to understand is that insurance is designed to cover unexpected events, not the gradual aging of your roof. The following are generally not covered:
- Normal wear and tear. A roof that has reached the end of its service life and needs replacing due to age is typically the homeowner's responsibility, not the insurer's.
- Lack of maintenance. Damage that results from neglected maintenance or an unaddressed existing problem is usually excluded.
- Pre-existing damage. Issues that existed before the event you are claiming for are generally not covered.
- Poor past workmanship. Damage stemming from a previous substandard installation may be excluded. Our page on poor workmanship covers how installation issues cause problems.
This distinction between sudden damage and gradual deterioration is at the heart of almost every roof insurance decision.
How Roof Age and Depreciation Affect Claims
The age of your roof can significantly affect how a claim is handled, and this catches many homeowners by surprise.
Replacement cost vs. actual cash value. Policies generally pay out in one of two ways. Replacement cost coverage pays what it costs to replace the damaged roof with a new one. Actual cash value coverage pays the depreciated value, meaning the roof's age is subtracted from the payout. An older roof on an actual cash value policy may result in a much smaller payment than the cost of a new roof.
Age limits and conditions. Some insurers apply conditions to older roofs, such as reduced coverage, higher premiums, or in some cases requiring the roof to be replaced to maintain coverage. As roofs age, insurers tend to become more cautious.
Deductibles. As with any claim, your deductible applies, so the amount you receive is reduced by whatever deductible your policy carries.
Because these terms vary so widely between policies, reviewing your own coverage, and asking your provider directly, is the only way to know exactly where you stand.
Steps to Take After Roof Damage
If your roof is damaged by a covered event and you are considering a claim, a few steps help protect your position:
- Document the date. Record the exact date the damage occurred. Insurers generally have a time limit for filing claims, so this matters.
- Notify your insurer promptly. Contact your insurance company as soon as possible after the damage.
- Document the damage. Take photos and notes. Our storm damage inspection guide walks through thorough documentation.
- Get a professional assessment. A professional inspection provides an objective record of the damage and its extent.
- Understand your right to choose. You have the right to choose your own contractor. Insurers sometimes recommend a contractor, but their suggestion may be driven by cost rather than quality. The choice is yours.
Our roof insurance claims page covers the claims process and the importance of choosing your own contractor in more detail.
How McKay Roofing Can Help
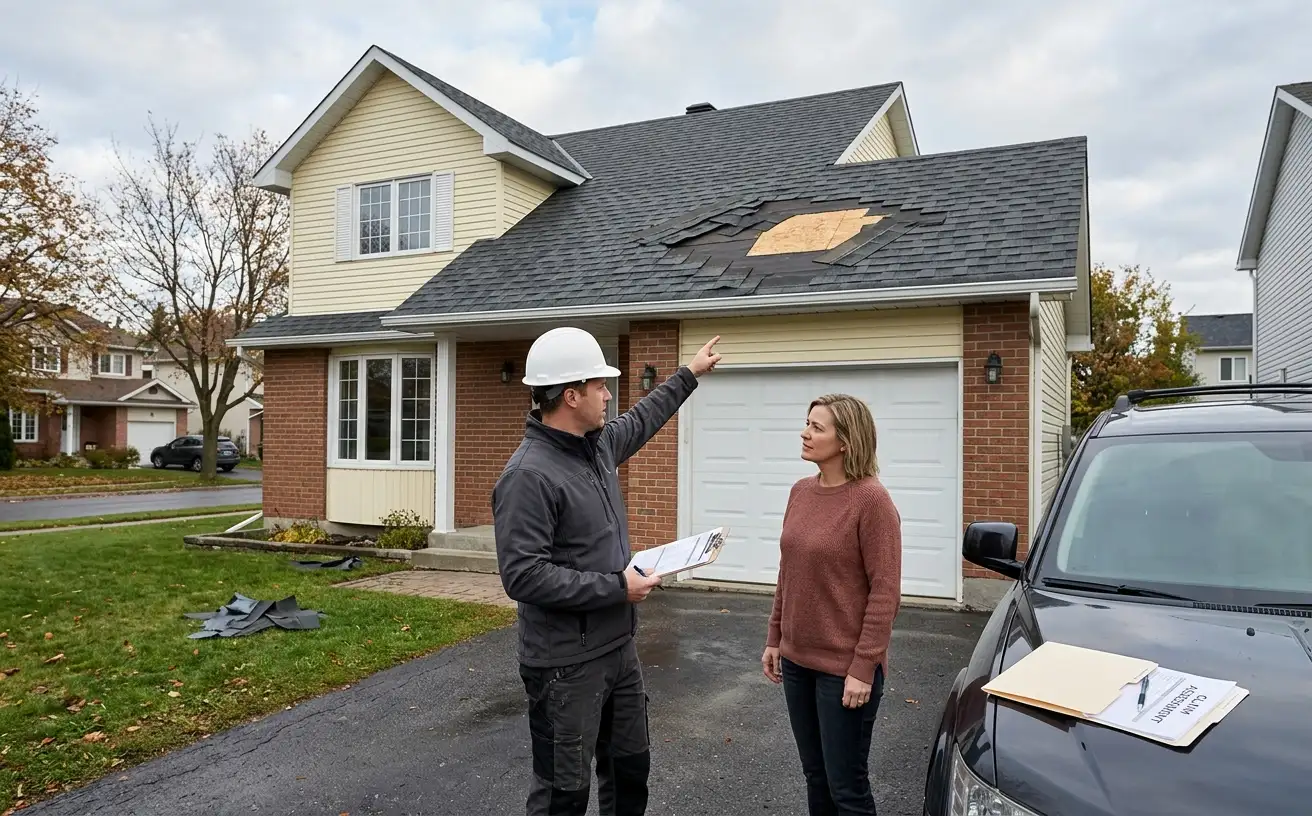
While we are not insurance advisors and cannot determine what your policy covers, we can help with the roofing side of an insurance situation in concrete ways. If you are unsure whether your roof has been damaged, we will arrange an inspection of your roof and provide your insurance company with a letter reporting our findings. That objective, professional assessment can be valuable when you are dealing with an insurer.
We also handle the actual repair or replacement work once a claim is settled, whether that is addressing shingle blow-offs from a windstorm, other roof repairs, or a full replacement. For commercial buildings, our commercial roof repair team handles the same. And because you have the right to choose your own contractor, you can choose an established, certified company rather than simply accepting whoever the insurer suggests.
Repair or Replace After a Claim
Whether a covered event leads to a repair or a full replacement depends on the extent of the damage. Localized damage from a fallen branch may be a repair, while widespread storm or hail damage across the roof may justify replacement. Our guide on roof repair vs. replacement explains how that decision is made, and the insurer's assessment of the damage will factor into what is covered.
A Note on Getting Accurate Information
Insurance coverage is specific to each policy and each situation, and the information here is general guidance rather than advice about your particular coverage. The best sources for definitive answers are your own insurance policy documents and a direct conversation with your insurance provider. Ask them specifically about how your policy handles roof damage, whether you have replacement cost or actual cash value coverage, and whether your roof's age affects your coverage. Knowing these answers before you have a problem puts you in a much stronger position.
Get Your Free Estimate
Dealing with roof damage and not sure of the extent? We can inspect your roof and provide your insurance company with a letter reporting our findings, and handle the repair or replacement once your claim is settled.
Fill out the form or reach us directly.
Call us at (613) 259-5766 or contact us to schedule an inspection.
Know Where You Stand
Home insurance in Ontario generally covers sudden, accidental roof damage like storms and hail, but not the gradual aging of a roof that has reached the end of its life. Roof age, depreciation, and the specifics of your policy all shape what you can expect. The clearest path is to understand your own coverage before you need it, document any damage carefully, and work with an established contractor you choose yourself. McKay Roofing is here to help with the inspection, documentation, and the roofing work itself whenever you need us.